A business paying an overseas supplier wants the money to arrive in a usable form. It may care less about the technology in the middle than about fees, timing and reconciliation. Mastercard’s March 17 agreement to acquire BVNK targets that middle: infrastructure connecting stablecoin payments with conventional money movement.
The announcement values the transaction at up to $1.8 billion, including $300 million in contingent payments. Mastercard says it expects the acquisition to close before the end of 2026, subject to regulatory review and customary conditions. An agreement has been signed; the announcement does not mean the acquisition is already complete.
The useful connection is at the edges
A stablecoin transfer can move a token between compatible participants. A commercial payment often starts and ends elsewhere: in bank accounts, treasury systems and invoices. Connecting those environments requires more than a transaction on a blockchain.
BVNK’s role, as described in the announcement, is to provide infrastructure linking fiat and stablecoin payments. Mastercard identifies uses including cross-border remittances, business payments and payouts. These are areas where the operational details can determine whether a new route is useful.
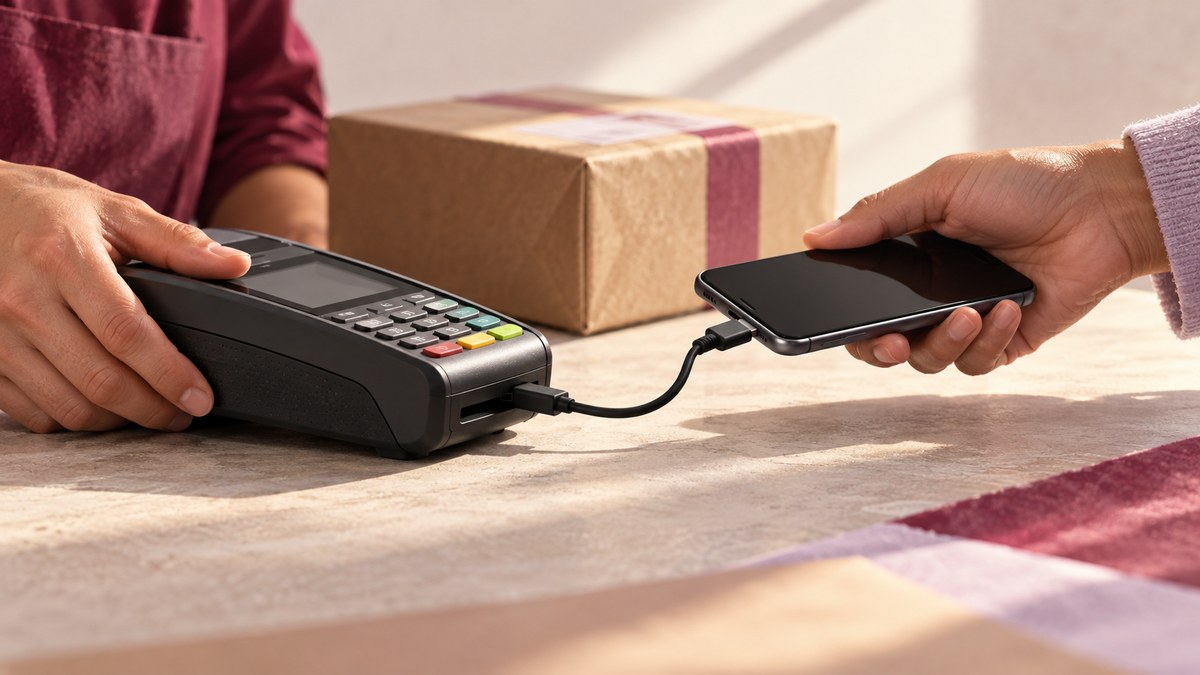
Imagine a company paying a contractor who wants local currency. The company needs to know what the recipient receives, when conversion occurs and what record returns to its finance team. Even if part of the transfer uses stablecoins, the service still has to explain those ordinary payment details.
A deal thesis is not a shipped integration
The proposed acquisition gives a clear indication of Mastercard’s intended direction. It does not establish that every Mastercard customer can immediately use BVNK’s capabilities through an existing contract or interface.
Integration takes decisions about products and availability. Customers will need to see which payment routes are supported and how the combined offering handles operational problems. A press release can explain the ambition without resolving those questions.
The price also needs to be read accurately. “Up to” includes the contingent component; it should not be flattened into an unconditional cash figure. That distinction matters when evaluating the scale of the transaction, even without attempting a valuation of the business.
For our Fintech desk, the most revealing part of the announcement is its focus on connecting systems people already use. The eventual product test will be whether a business can send, receive and account for a payment with less friction. The acquisition agreement is a step toward that proposition, not proof of the outcome.
Reporting & Sources
Based on Mastercard’s March 17, 2026 acquisition announcement. Closing expectations and business objectives are attributed to Mastercard. The payment example is illustrative.